The Homebuyer’s Corner
Mortgage Prequalification vs Preapproval vs Underwritten Approval in California
Written by Armando Novelo, NMLS 237243, a mortgage loan officer in West Covina with over 20 years of experience helping Southern California buyers.
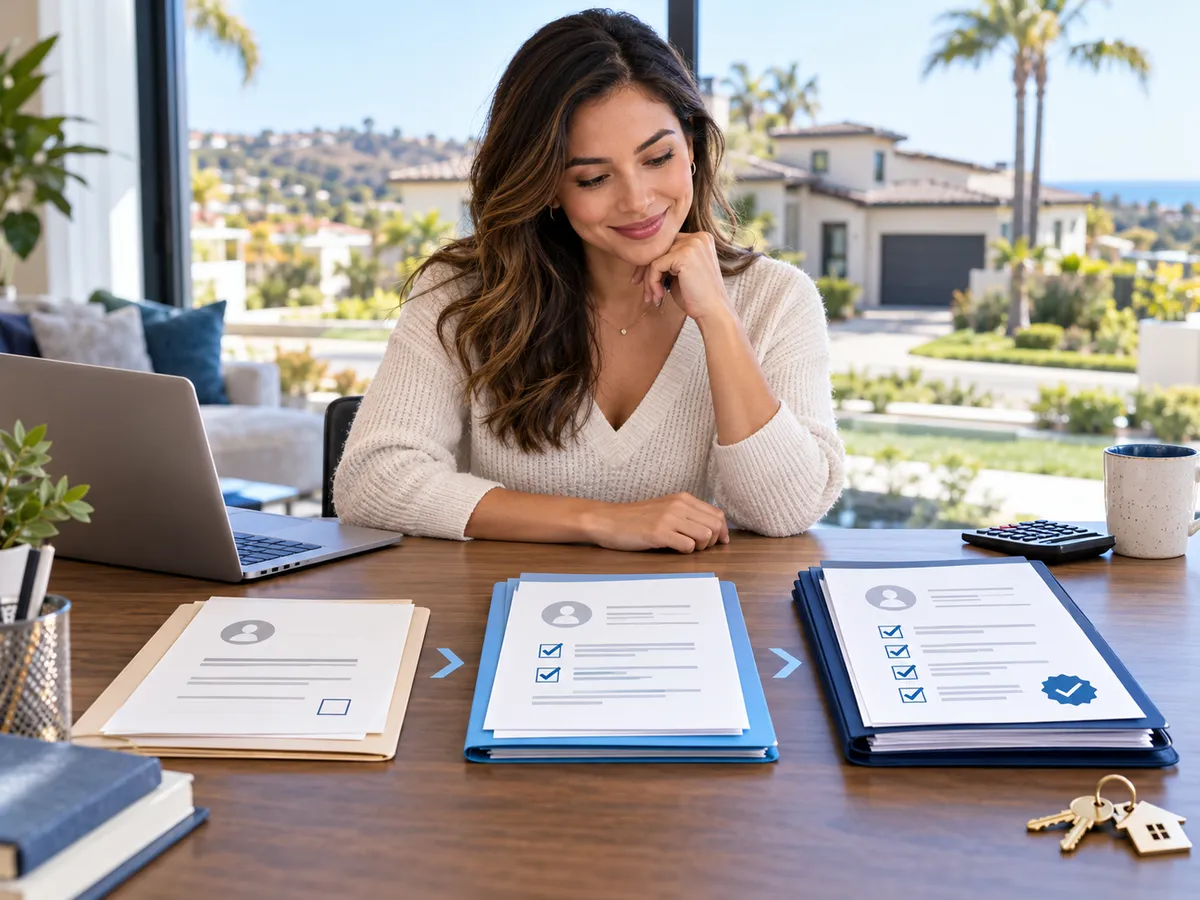
A mortgage prequalification, preapproval and underwritten approval can represent very different levels of review, but the labels are not standardized from one lender to another. The Consumer Financial Protection Bureau says lenders use the terms "prequalification" and "preapproval" differently, which is why Armando Novelo tells California homebuyers to focus less on the name of the letter and more on what the lender has actually verified.
Whenever possible, Armando prefers to have a buyer's financing reviewed as deeply as possible before the buyer starts making offers. The goal is simple: find financing problems early and give the seller a stronger reason to believe the buyer can close.
What Is a Mortgage Prequalification?
A mortgage prequalification is often an early estimate of what a buyer may be able to borrow, but the amount of verification behind it depends on the lender.
Some lenders issue a prequalification using information the buyer reports without fully verifying the supporting documents. Other lenders use the term differently. The Consumer Financial Protection Bureau specifically warns buyers that the words alone do not tell them how much work a lender has actually completed.
That is why Armando does not want a buyer assuming a quick letter means the financing has been thoroughly reviewed. Income can look straightforward until bonus, commission, overtime, self-employment, job history or another detail changes how it is calculated. Bank balances can look strong until a large deposit has to be sourced. Credit can look fine until something on the report needs a closer look.
The letter matters. The work behind the letter matters more.
What Is a Mortgage Preapproval?
A mortgage preapproval generally means the lender has evaluated the buyer's finances and is tentatively willing to lend up to a certain amount, but the depth of that review still varies by lender.
The CFPB describes a preapproval letter as a lender's statement that it is tentatively willing to lend up to a certain loan amount. It also makes clear that the letter is based on assumptions and is not a guaranteed loan offer. Buyers can read the CFPB's current preapproval guidance here.
Armando's concern is not whether a piece of paper says "preapproved." He wants to know what has actually been checked. Was the credit report reviewed? Were income documents analyzed? Were assets verified? Were unusual deposits explained? Was variable income calculated correctly? Has anyone looked for the kind of issue that could turn into a problem once the buyer is already in escrow?
A preapproval can be a very useful tool. Armando just does not assume every lender's preapproval means the same thing.
If you want to understand what lenders are reviewing behind the scenes, Armando's guide to what lenders actually look at during mortgage approval explains the income, credit, assets and debt review in more detail.
What Is an Underwritten Mortgage Approval?
An underwritten approval goes a step further because the buyer's financial file has gone through a more complete underwriting review before a specific property is under contract, when the lender and loan program allow it.
Armando's team refers to this as pre-underwriting. Income, assets, credit, employment and the supporting documentation are reviewed upfront so potential financing questions can be addressed before the buyer finds the home.
The term "underwritten approval" is not a universal legal label used exactly the same way by every lender, so buyers should still ask what the approval actually includes. The important distinction is whether the file has received a comprehensive underwriting review rather than only an initial loan officer review or automated estimate.
Fannie Mae's current underwriting guidance explains that lenders are responsible for confirming the accuracy and completeness of the borrower's information and for evaluating credit history, income, employment, assets and other financial information used to qualify the borrower. Buyers can review that framework in Fannie Mae's Desktop Underwriter guidance.
Does an Underwritten Approval Guarantee My Loan Will Close?
No. An underwritten approval reduces some borrower-side financing uncertainty, but it does not guarantee the mortgage will close.
A property still has to be identified and meet the requirements of the loan. The lender may still need an acceptable appraisal, title and property documentation, updated borrower documents and satisfaction of any remaining conditions. A material change in the buyer's finances can also affect an approval.
The CFPB's regulations recognize a similar distinction in formal preapproval programs. Even after a comprehensive analysis of the buyer's creditworthiness, a written commitment can still be conditioned on identifying an acceptable property and on there being no material change in the applicant's financial condition or creditworthiness. Buyers can review that definition in Regulation C.
Armando sees the underwritten approval as a way to move more of the borrower review to the front of the process. It does not remove every condition that comes later.
Can an Underwritten Approval Help My Offer Get Accepted?
It can make the financing side of an offer more reassuring to a seller, especially when the seller is comparing otherwise similar offers, but it does not guarantee that your offer will win.
The CFPB notes that a preapproval helps show a seller that a buyer is likely to be able to obtain financing. Armando takes that concept further when a file can be pre-underwritten because he can tell the buyer's agent that more of the borrower's financial review has already been completed.
That can matter in a competitive California transaction. A seller is not only comparing prices. The seller is also deciding which offer appears most likely to reach the closing table without a financing surprise.
Armando would never tell a buyer that an underwritten approval automatically beats another offer. Price, contingencies, closing timeline, property terms and the seller's priorities still matter. The advantage is that the buyer can present a more developed financing story.
Why Does Armando Pre-Underwrite Buyers Whenever Possible?
Armando pre-underwrites buyers because he would rather uncover a financing question before an offer is accepted than while the buyer is already under contract.
This is where his experience matters most. Files can contain things that look small at first and become much bigger once an underwriter reviews them. An unusual bank deposit may need documentation. Bonus or commission income may need a history before it can be counted. A recent job change may need more explanation. A credit item may affect the loan differently than the buyer expected.
Armando's process is to get those questions out in the open while there is still time to solve them calmly.
That is also why he encourages buyers to start the mortgage process before they feel rushed. His article on why starting the mortgage process early matters explains why extra time gives buyers more options when something needs attention.
What Should I Ask My Lender Before I Make an Offer?
Ask one simple question: has an underwriter actually reviewed and approved my financial file?
Then ask what is still outstanding.
That question tells you more than the word printed at the top of the letter. A lender may call something a preapproval even though the file has not been fully underwritten. Another lender may have already completed a much deeper review.
Armando wants buyers to know where they truly stand before they start competing for a home.
Is It Worth Getting Pre-Underwritten Before I Start Shopping?
For buyers who are serious about making offers soon, Armando believes deeper upfront review is worth doing whenever the lender and loan program allow it.
The benefit is not just a stronger letter. It is the chance to identify financing issues before the buyer falls in love with a house and the escrow clock starts running.
Armando has seen the same pattern over and over in California transactions: the earlier a financing question is found, the more options the buyer usually has to address it. Waiting until after an offer is accepted turns the same question into a deadline.
A prequalification can tell you where to start. A preapproval can tell you much more. When a file can be fully reviewed in advance, an underwritten approval can give the buyer and the people evaluating the offer another level of confidence in the financing.
The important question is not what your lender calls the letter.
It is how much of your file has actually been reviewed.
Not sure how ready you are to make an offer? Start with Armando's buyer readiness quiz to see where you stand. If you are ready for the next step, you can choose a time to talk with Armando about your path toward buying a home.
Armando Novelo, NMLS 237243, is a mortgage loan officer at Super Mortgage Bros, powered by Golden Empire Mortgage. He has been helping Southern California buyers and homeowners since 2002. His office is located in West Covina, CA.
Article Published: October 15, 2026
Last modified: October 15, 2026
Last reviewed: October 15, 2026
Links
Contact
Armando Novelo
NMLS 237243
Super Mortgage Bros
1900 W. Garvey Ave S. #100
West Covina, CA 91790
Phone: (626) 200-1838
I agree to be contacted by Super Mortgage Bros via call, email and text. To opt out, you can reply “stop” at any time or click the unsubscribe link in the emails. Message and date rates may apply.
Message frequency varies
© 2026 Super Mortgage Bros. Super Mortgage Bros. | All Rights Reserved | Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Golden Empire Mortgage, Inc. ("GEM") [NMLS ID No. 2427] is a California corporation whose principal business office is located at 1200 Discovery Drive, Ste. 300, Bakersfield, California 93309. GEM is a residential mortgage lender and servicer Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. under license no. 413-0360. https://www.nmlsconsumeraccess.org